Contact center of the Ukrainian Judiciary 044 207-35-46
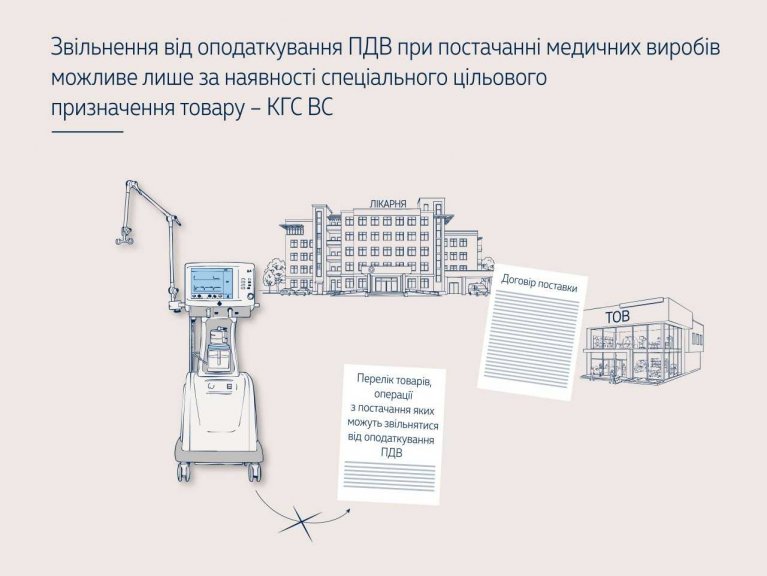
Exemption from VAT applies only where the conditions prescribed by law are present concurrently, in particular where the medical device is included in the relevant list and is intended for the provision of medical care to persons who have sustained a wound, contusion or other injury to health. The mere fact that medical equipment has been purchased by a healthcare institution is insufficient.
This conclusion was reached by a panel of judges of the Commercial Cassation Court within the Supreme Court.
The head of a prosecutor’s office, acting in the interests of the state in the person of a city council, brought a claim against the Central City Hospital and a limited liability company seeking a declaration that a supply contract was invalid in so far as it included VAT in the contract price, and recovery of that sum as monies paid without legal basis. The claim was founded on the assertion that the operations of importation and supply within the customs territory of Ukraine of the CWH-3010 Laurent® artificial lung ventilation apparatus (ventilator) fall within the category of operations exempt from VAT, and that the parties’ inclusion of the amount of VAT in the price of the goods was therefore without foundation.
The commercial court, by a judgment left unchanged by a resolution of the appellate commercial court, dismissed the claim. The courts proceeded on the basis that, although the ventilators are included in the relevant list of goods the supply of which may be exempt from VAT, the prosecutor had failed to prove their special designated purpose for the provision of medical care to the category of persons defined by law.
In reviewing the case, the Commercial Cassation Court of the Supreme Court observed that a medical device purchased by a healthcare institution is exempt from VAT pursuant to sub-paragraph 2 of paragraph 32 of subsection 2 of section XX of the Tax Code of Ukraine, provided that its purpose is established — namely, the provision of medical care to natural persons who, during the period of the anti-terrorist operation and/or the taking of measures to ensure national security and defence, to repel and deter armed aggression, and/or the introduction of martial law, sustained a wound, contusion or other injury to health.
The courts found that the hospital had purchased two ventilators for the provision of medical care to residents of the district. At the same time, neither the tender documentation nor the supply contract contained any information indicating that the equipment was being procured specifically for the provision of assistance to the special category of persons.
The Commercial Cassation Court of the Supreme Court observed that exemption from VAT applies only where three conditions are present concurrently: the medical devices are supplied for use by the relevant institutions or persons; they are intended for the provision of medical care to the category of persons defined by law who have sustained a wound, contusion or other injury to health; and they are included in the relevant list approved by the Cabinet of Ministers of Ukraine. The absence of even one of these conditions precludes the application of the relief.
The Supreme Court indicated that what is determinative for exemption from VAT is not merely the category of the goods and the identity of the recipient of such goods, but also the designated purpose of the goods — namely, the provision of medical care to natural persons who, during the period of the anti-terrorist operation and/or the taking of measures to ensure national security and defence, to repel and deter the armed aggression of the Russian Federation, and/or the introduction of martial law in accordance with the legislation, sustained a wound, contusion or other injury to health.
Since the hospital had not defined any special designated purpose for the procurement, and the purchased medical devices are used for the provision of medical care to various categories of persons, there were no grounds for applying the preferential VAT regime.
As a result of the cassation review, the cassation appeal was dismissed and the decisions of the lower courts were left unchanged.
Resolution of the Commercial Cassation Court of the Supreme Court of 23 June 2026 in case No. 916/2438/25 – https://reyestr.court.gov.ua/Review/137926876.
This and other legal positions of the Supreme Court can be found in the Database of Legal Positions of the Supreme Court - https://lpd.court.gov.ua.
